
Accounts Receivable Accounting: A Guide for NZ Businesses
Your sales look fine. Your profit and loss might even show a good month. But the bank balance is tight, GST is coming up, and two decent-sized invoices still haven’t been paid.
That’s the cash flow puzzle a lot of Auckland business owners and property investors are dealing with. The work is done, the invoice is out, but the money isn’t in the account yet. In practice, that gap is where accounts receivable accounting stops being a bookkeeping topic and becomes a business survival topic.
The Common Cash Flow Puzzle for NZ Businesses
A common example goes like this. A trades business finishes several jobs in a month and sends the invoices straight away. On paper, revenue has been earned. In the bank, there’s still not enough cash to comfortably cover wages, suppliers, and the next GST payment.
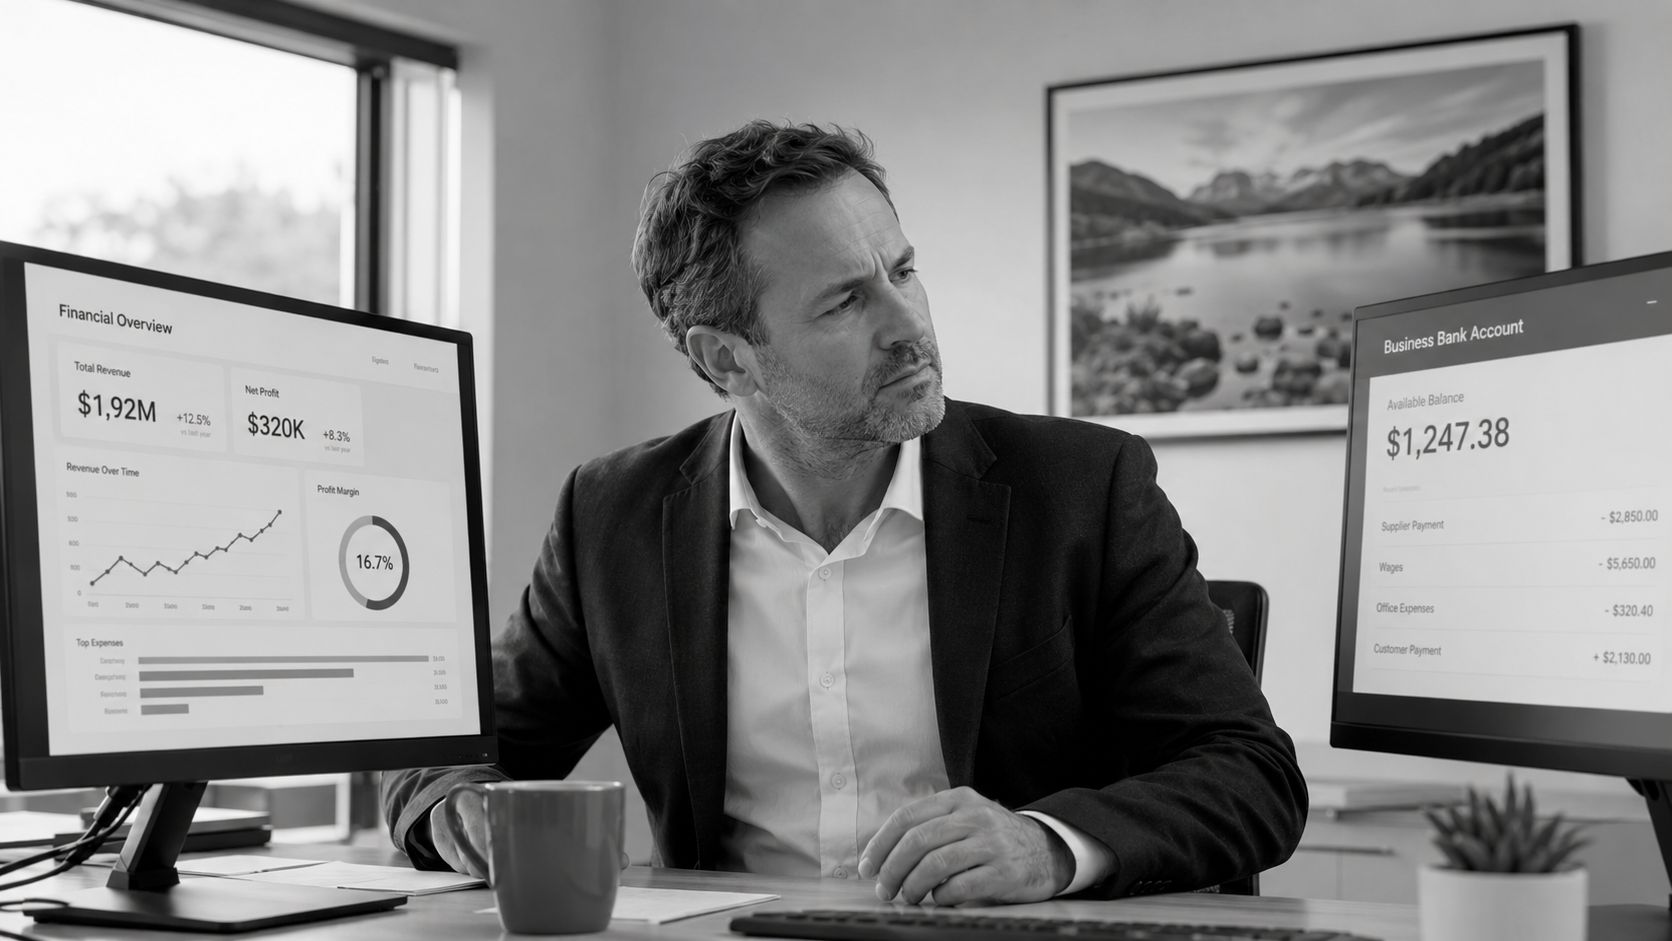
That gap exists because in New Zealand, accounts receivable is part of accrual accounting. Revenue is recognised when it’s earned, not when cash is received, so unpaid customer invoices sit on the balance sheet as a current asset. For SMEs, that directly affects cash-flow forecasting, debtor follow-up, and the pressure around GST and regular compliance cycles, as outlined in NetSuite’s explanation of accounts receivable.
Profit can look healthy while cash is under pressure. The unpaid invoices in between are usually the reason.
This is why many owners feel confused by their own numbers. They aren’t doing anything “wrong”. They’re just seeing the difference between earning income and collecting cash. Once you understand that difference, the next steps become much clearer.
Understanding Accounts Receivable Fundamentals
Think of accounts receivable as your business’s official IOU list. It records what customers owe you for work you’ve already done or goods you’ve already supplied.
Under accounting standards used in New Zealand, AR is recognised as a current asset once goods or services are delivered and invoiced. It also needs to be shown at net realizable value, which means the amount you expect to collect, rather than the full invoice total. That’s why businesses may need an allowance for doubtful debts.
What gets recorded
When you issue an invoice on credit, the basic accounting effect is simple:
- Accounts receivable goes up
- Revenue goes up
When the customer pays later:
- Cash goes up
- Accounts receivable goes down
That’s the core reason profit doesn’t always match cash.
Why this matters in real life
If you send an invoice today and payment turns up weeks later, your accounts may already show income while your bank account still feels empty. That’s normal under accrual accounting, but it also means owners need better debtor visibility.
Learn more: Business owners who want that next layer can read this guide on accounts receivable turnover.
Practical rule: If an invoice is old enough to worry you, it’s old enough to review for collectability.
Your Practical AR Management Toolkit
The most useful AR tool for most small businesses isn’t fancy software. It’s a good aging report, reviewed every month.
In NZ, trade receivables are commonly expected within 30–60 days, and the risk of non-collection rises as balances move into older buckets. A monthly aging review helps with cash forecasting, spotting problem accounts early, and checking whether receivables are turning into real cash.
Start with the aging report
An aging report groups invoices by how overdue they are. That tells you far more than a single total AR balance ever will.
| Customer Name | Total Due | Current (0-30 days) | 31-60 Days | 61-90 Days | 90+ Days |
|---|---|---|---|---|---|
| Customer A | $ | $ | $ | $ | $ |
| Customer B | $ | $ | $ | $ | $ |
| Customer C | $ | $ | $ | $ | $ |
Call it what it is. If most of your receivables are sitting in older buckets, your cash flow is weaker than your profit report suggests.
What to look for each month
- Concentrated exposure: One customer making up too much of your receivables creates risk if they slow down payment.
- Bucket drift: Invoices moving from current into 31 to 60 days are an early warning sign, not an admin nuisance.
- Repeated excuses: Customers who always promise payment “next week” often need tighter terms or firmer follow-up.
A practical collection routine matters more than good intentions. Prompt invoicing, clear due dates, regular reminders, and consistent escalation usually work better than waiting and hoping. For owners wanting more practical debtor steps, this guide on simple strategies to get paid faster is useful.
Keep an eye on turnover
A standard AR measure used in practice is the AR turnover ratio:
AR turnover ratio = net credit sales ÷ average accounts receivable
A higher turnover generally means you’re collecting more efficiently. A lower turnover can point to loose credit control, slow-paying customers, or disputes sitting unresolved.
The GST trap for NZ businesses
Many owners experience real pressure in this situation. You can issue an invoice, recognise the revenue, and still be waiting on payment while a tax obligation is already approaching.
For NZ businesses, GST can create a timing mismatch. Depending on the basis used, GST is generally payable in the period the invoice is issued or payment is received. That means an unpaid debtor can still add pressure to your cash position before the customer has paid. In practice, AR management and GST planning need to sit together, not separately.
A sale on credit can improve profit and tighten cash at the same time.
Streamline Your Receivables with Xero
Many NZ businesses no longer manage debtors from a manual ledger or wait until month-end to see what’s overdue. That shift matters because speed matters in collections.
Xero was founded in Wellington in 2006 and changed how local SMEs handle receivables. It moved many businesses from manual debtor tracking to real-time visibility, including aging buckets such as 0–30, 31–60, and 90+ days.
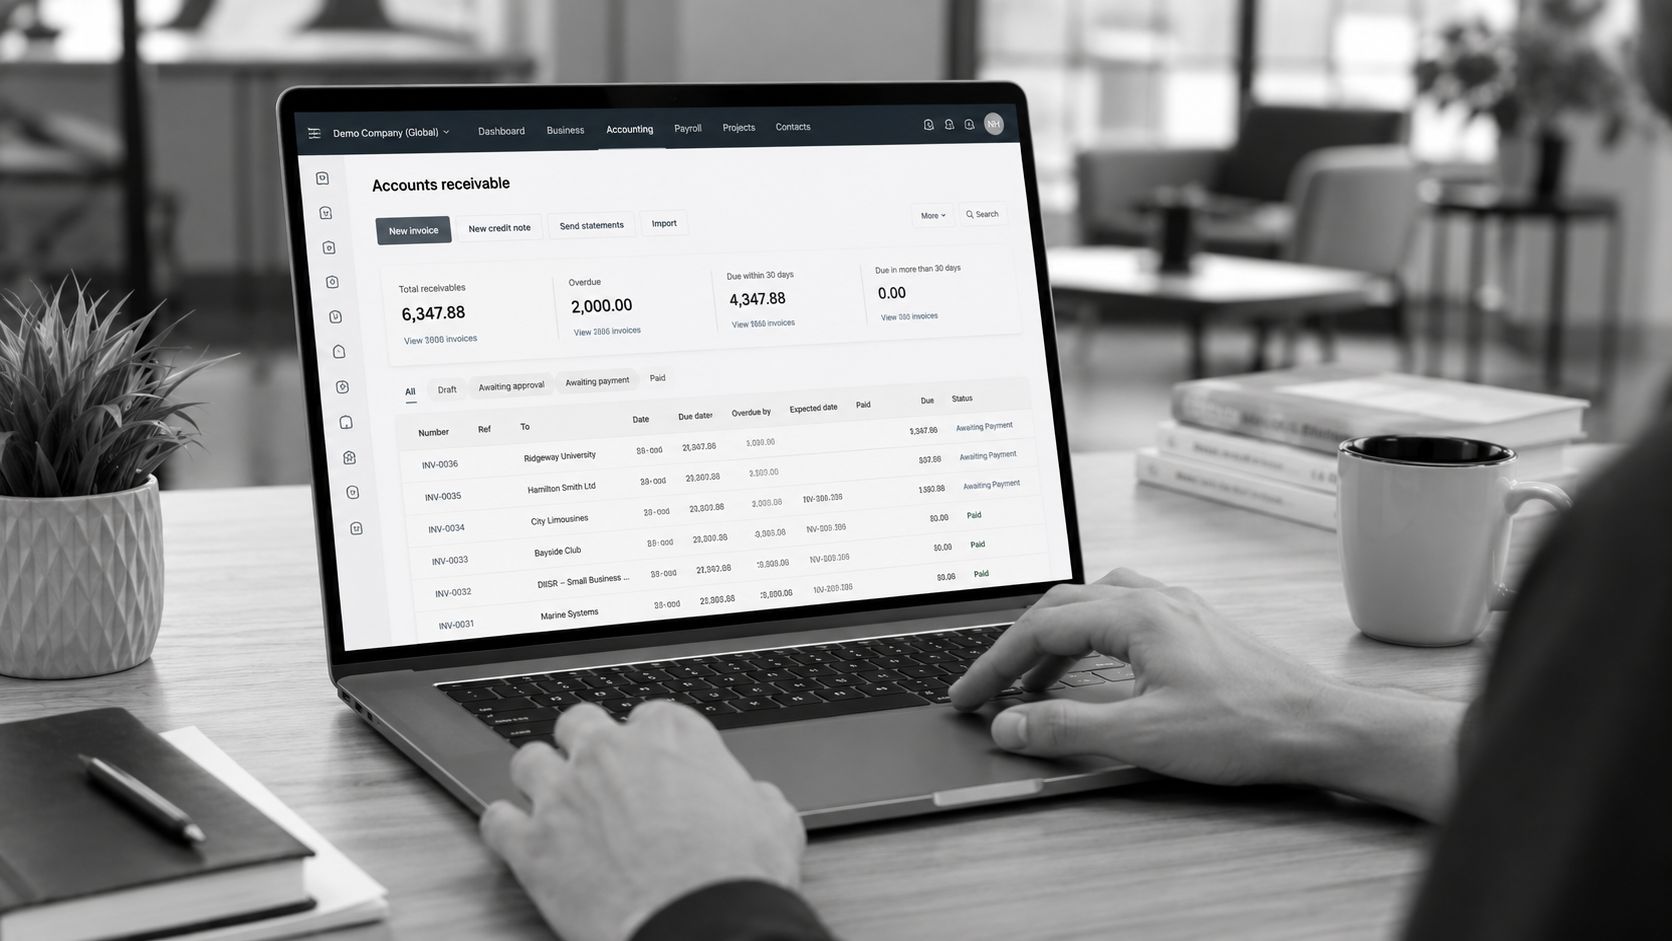
What works better in Xero
A good Xero setup helps with day-to-day debtor control:
- Automated reminders reduce the awkwardness of chasing every invoice manually.
- Live dashboards show what’s current and what needs attention now.
- Online payment options can remove friction for customers who mean to pay but delay the admin.
Some businesses also look at outside examples of Xero bookkeeping services to understand what parts of debtor management can be handed off or tightened up with better systems.
For Auckland owners who want this managed properly, Business Like NZ Ltd works with Xero as a Platinum Partner and supports setup, reporting, and cash-flow visibility as part of broader accounting and advisory work.
When Good Invoices Go Bad in New Zealand
Most unpaid invoices don’t become bad debts overnight. They slide there. The warning signs usually show up first in your aging report, customer communication, and payment behaviour.
Stats NZ reported 2,682 business liquidations in the year ended March 2025, up from 2,433 in the prior year, which is a useful reminder that collectability needs active judgement, not passive hope, as discussed in this receivables collectability context.
Signals that should trigger a review
Not every late invoice is a bad debt. Some are admin delays. Some are genuine disputes. Some are a sign the customer is under strain.
Review collectability more closely when you see:
- Aging getting worse: Balances keep shifting into older buckets without a clear payment plan.
- Changed payment patterns: A customer who used to pay on time starts paying late repeatedly.
- Concentration risk: Too much of your receivables is tied to one client or one sector.
- Communication dropping off: Calls and emails go unanswered, or promises stop matching action.
Allowance versus write-off
An allowance for doubtful debts is a provision. You’re recognising that some receivables may not be collected, even if you haven’t given up on a specific invoice yet.
A write-off is the next step. That means you no longer expect to collect that particular debt and remove it from receivables. The exact tax and GST treatment depends on your circumstances, records, and basis of accounting, so it’s worth getting advice before processing it.
If you want a practical collection workflow before matters get that far, this dunning process guide gives a helpful overview of staged follow-up. For NZ-specific action on overdue accounts, this guide on how to collect unpaid invoices is a good starting point.
Don’t wait for a debtor to fail before treating them as a risk. Payment behaviour usually tells you earlier.
Take Control of Your Business Cash Flow
Good accounts receivable accounting helps you answer a simple question. How much of your “income” is in the bank, and how much is still just a promise to pay?
When you review aging monthly, watch receivable quality, keep GST timing in mind, and act early on weak debtors, you put yourself back in control. That usually means fewer surprises, better cash forecasting, and less stress around payroll, suppliers, and tax dates.
The goal isn’t perfect debtors. It’s a business that doesn’t get caught out because profit looked better than cash.
If you want practical help with receivables, GST timing, Xero reporting, or cash-flow forecasting, Business Like NZ Ltd supports Auckland businesses and property investors with down-to-earth chartered accounting advice. They work with owners who want more financial freedom, less time lost to admin, and less stress from unclear numbers.