
Buying Investment Property NZ: A Complete Guide
The loudest advice on buying investment property NZ is usually the worst: get pre-approval, chase the highest rent, and move fast. That’s how people end up with properties that look good on paper and drain cash in real life.
A better rule is simple. Bank approval is the start of the test, not the finish line. In New Zealand, the market is active, with 79,600 properties bought and sold in the 12 months to January 2026, above the long-term average of 78,000 and well above the cycle low of 56,000 (Opes Partners). That turnover matters, but it doesn’t change the basics. A deal still has to survive vacancy, repairs, lending rules, and your own cashflow.
Why Bank Approval Does Not Mean the Deal Works
A bank saying yes only means the lender is willing to fund the loan. It does not mean the property is a sound investment, and it certainly does not mean the numbers will survive once real costs, vacancy, and repairs show up.
Stress-test the deal like an accountant, not a punter
A common mistake is to build a spreadsheet around full occupancy, today’s interest rate, and a generous maintenance allowance. That is weak analysis. A proper model should show what happens if rent is missed for a period, an early repair bill lands, or borrowing costs rise. If the deal only works in the neat version of the world, it is too fragile to buy.
Run the numbers against real setbacks, not wishful thinking. Vacancy, tenant turnover, insurance, rates, and unexpected maintenance all hit cashflow faster than many first-time buyers expect. A property can still look fine on paper and fail the moment one of those costs arrives.
Practical rule: if the property only works in the best-case scenario, it’s not a deal. It’s a hope.
Use three versions of every listing. Base case, bad case, and ugly case. If the ugly case still leaves you standing, the deal deserves a closer look. If it does not, walk away.
Understanding Deposit Requirements and Borrowing Power
Work out the bank position before you even open listings. For most NZ investors, an existing investment property generally needs at least a 30% deposit, while a new build can be bought with 20% because new builds are exempt from the standard investor LVR restriction (Opes Partners). That difference changes the slice of the market you can buy in, and it changes how much cash you need to keep back for repairs, rates, and vacancy.
Put borrowing capacity ahead of suburb ranking
The common error is starting with a suburb and hoping the finance will work later. Do it the other way around. Check your income, savings, and equity first, get pre-approval, then test the property against gross yield, net yield, and downside scenarios. Banks also count only part of the expected rent in serviceability, so a tidy headline yield is not enough on its own.
That filter matters because the primary constraint is borrowing capacity, not postcode appeal. A strong-looking regional return can still be out of reach if debt servicing is tight. If the numbers only work by assuming full rent, no repairs, and perfect tenant behaviour, the purchase is too thin. Build in room for vacancy, insurance, rates, and maintenance before you sign anything.
Choosing the Right Ownership Structure and Tax Settings
The biggest savings in property often come from getting the ownership structure right before you buy, not from chasing a single deduction later. Personal name, company, and trust all come with trade-offs, and the wrong structure can lock you into expensive clean-up work later.
Get the structure right before the offer goes unconditional
A common mistake is buying a second or third rental without thinking through succession, asset protection, future sale plans, or how the lending will sit across the portfolio. Then the owner discovers the structure was convenient for day one but awkward for day five. That’s when restructuring costs start piling up.
The tax side also needs sober thinking. Depreciation, bright-line, interest deductibility, and GST can all interact differently depending on how the property is held. For NZ-specific structuring, use this ownership guide for rentals as the starting point, then get advice before signing.
The commercial decision should come first. The structure should support it, not rescue a bad purchase.
If you’re buying for long-term hold, plan for flexibility. If you’re buying for a shorter hold or future family transfer, that changes the picture again.
Running Due Diligence Beyond the Headline Rent
A property can look tidy from the roadside and still carry a nasty bill in the background. That’s why headline rent is a trap. The key question is whether the net yield still works after management fees, compliance costs, vacancy, and future capital expenditure.
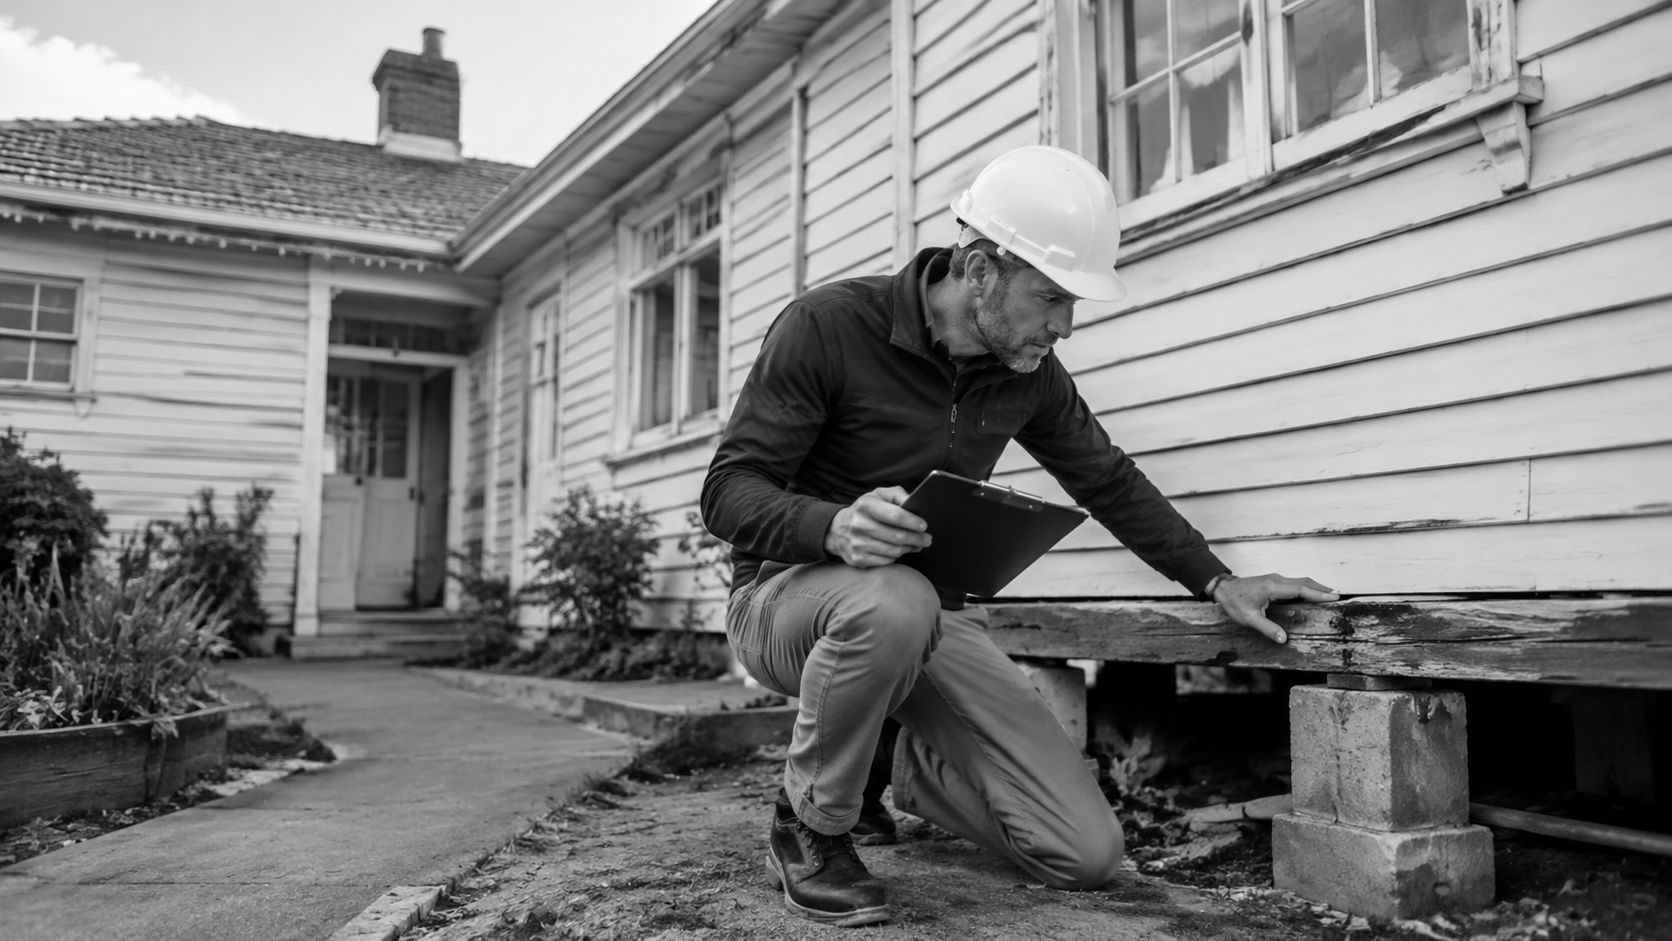
Check the building, the paperwork, and the hidden costs
A proper workflow in New Zealand starts with a building inspection and LIM report, then extends to insurance, title review, and tenancy checks before you go unconditional.
I’ve seen deals where the rent looked fine until maintenance and compliance upgrades were added back into the forecast. Once those costs were included, the expected return changed sharply. In those cases, the better move wasn’t to panic. It was to renegotiate the price, revise the cashflow, and budget for future capital work from day one.
For a simple return check, use this ROI guide and then subtract reality from it. If the property only works on gross figures, it doesn’t work.
Navigating the Purchase and Settlement Process
One of my clients nearly signed unconditionally on a villa because the rent looked strong and the agent kept pushing. The solicitor’s review then picked up a tenancy issue and an incomplete record set for deductible expenses. That was the point where the buyer still had an advantage.
Conditional first, unconditional only when everything is checked
Make the offer conditional, then clear finance, legal, and insurance before the unconditional date. That date is the commitment point. Once you go unconditional, you’re in.
Your solicitor or conveyancer should verify title, tenancy status, and the documents that support deductible expenses before settlement. Don’t treat that as admin. It’s the difference between a clean purchase and a messy one. A separate bank account for rental income and expenses is smart from day one, because it keeps IR3 reporting cleaner and the audit trail easier to follow.
The lesson is boring, and that’s exactly why it matters. Boring usually saves money.
Setting Up Post Purchase Accounting and Ongoing Compliance
Settlement isn’t the finish line. It’s the point where the property turns into a business record set, and if you don’t set that up properly, you’ll pay for it later in time, stress, and missed claims.
Build the systems before the first rent payment arrives
Open a separate bank account for the property and set up your accounting file straight away. Xero is a sensible starting point for many landlords. The point isn’t the brand. It’s clean categorisation, rent tracking, and visibility over what the property is really doing.
If you want a practical overview of the admin side, this rental accounting guide shows why the accounting setup matters. Keep a compliance calendar for tax filings, periodic reviews, and cashflow forecasts. That way, you spot problems early instead of finding them at year-end.
Business Like NZ Ltd also offers a Property Investor Package, and that sort of support is most useful when the investor wants straight answers, tidy records, and less time lost to admin. The right accounting set-up gives you time back and makes future decisions easier.
Frequently Asked Questions About NZ Investment Property
Can overseas buyers purchase residential property in NZ? The rules are strict. In general, a person needs a residence-class visa, must have lived in NZ for at least 12 months, and must have been physically present for more than 183 days in that period to be treated as ordinarily resident for residential property buying purposes (LINZ).
How long should I plan to hold an investment property? Plan for 7 to 10 years, and some NZ guidance recommends 10+ years to reduce cycle risk (Faisandier Homes).
What Auckland metrics matter most? Track gross yield, vacancy, and median weekly rent. The context provided for Auckland points to gross yields of about 3.5% to 4.5%, vacancy around 2.5%, and median rent around $650 per week, but suburb-level numbers matter more than city averages.
Are regional markets better than Auckland? Sometimes. Recent NZ market lists point to places like Rolleston and Kaiapoi/Rangiora as undervalued, with both yield and population growth signals worth a close look (Opes Partners). Don’t chase the label. Chase the numbers.
If you want straight, practical help with buying investment property NZ, talk to Business Like NZ Ltd. They help Auckland businesses and property investors get the structure, tax, and reporting right so you spend less time on admin and less energy worrying about mistakes. Visit Business Like NZ Ltd to get clear advice that’s down to earth and affordable.